
BEPS Pillar Two & Global Minimum Tax
Software – CCH Tagetik
Book a Pillar Two Readiness Assessment
Pillar Two live in 15 weeks · GloBE + QDMTT + IIR automated · 250+ projects · Platinum Partner
Our solutions

Corporate Tax Solution
Kickstart BEPS Pillar Two reporting with a controlled, end-to-end Global Minimum Tax process.
Time is running out for multinational groups to adapt to the OECD’s BEPS Pillar Two model rules. This directive strikes at the center of the financial close and consolidation process, adding new data requirements, complex calculations, and additional governance. Inulta helps you turn this into a repeatable, auditable process that aligns Finance and Tax, improves traceability, and keeps reporting on time, every time.
Why Pillar Two Compliance Cannot Run on Spreadsheets
BEPS Pillar Two – the OECD’s global minimum tax – requires multinational groups with revenues above €750 million to calculate an effective tax rate for every jurisdiction they operate in, apply the GloBE rules, and file a GloBE Information Return covering hundreds of data points per jurisdiction.
The data required – deferred taxes, covered taxes, substance-based carve-outs, entity-level adjustments – sits across ERP systems, consolidation platforms and local tax filings. Collecting it manually, every reporting period, across every jurisdiction, is not a sustainable process. It is a compliance risk with a filing deadline attached.
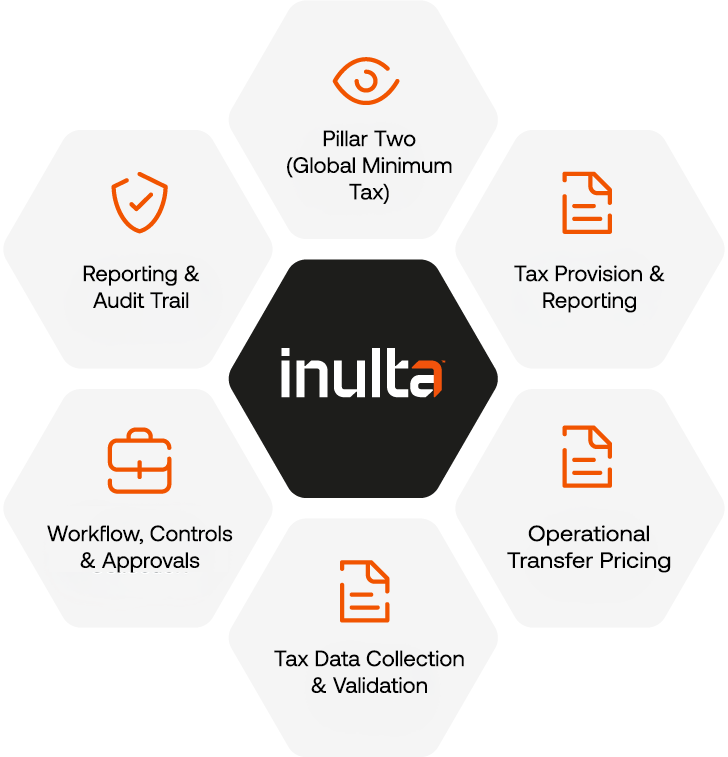
CCH Tagetik Corporate Tax automates the full Pillar Two cycle: data collection, GloBE calculations, top-up tax allocation and GIR preparation – on the same platform already used for financial consolidation.
What CCH Tagetik Global Minimum Tax Delivers
Pillar Two compliance is a data problem before it is a tax problem. The calculations themselves are defined by the GloBE rules – what varies between organizations is whether the data feeding those calculations can be produced reliably, every period, across every jurisdiction. CCH Tagetik addresses all three stages of that process.
Automated GloBE calculations – ETR, top-up tax, QDMTT, IIR
Jurisdictional effective tax rates, substance-based income exclusions, top-up tax under the Income Inclusion Rule (IIR) and Qualified Domestic Minimum Top-up Taxes (QDMTT) – calculated automatically from governed data, with full traceability from result back to source.
Jurisdiction-level data collection
Pre-built data models collect the GloBE data points from ERP systems, consolidation data and local inputs – with validation rules, workflow approvals and an audit trail for every figure. Safe harbour tests run automatically, reducing full calculations to the jurisdictions that actually need them.
GloBE Information Return (GIR) filing
The GloBE Information Return is generated directly from the calculation engine – no re-keying, no reconciliation between the numbers you calculated and the numbers you file.
Pillar Two Readiness – Live in 15 Weeks
Pillar Two deadlines do not wait for multi-year transformation programs. Inulta’s implementation approach delivers a working Pillar Two compliance environment in as little as 15 weeks – data model, GloBE calculations and GIR output – with scope extended in later phases as requirements evolve.
Go-live timeline of 15 weeks
Partnering with Inulta to implement the CCH Tagetik Global Minimum Tax solution allowed us to meet our reporting deadlines without compromising on data quality or usability. Their responsiveness and expertise made the implementation smooth and efficient, giving us a scalable solution for the future.
Michael McNamara, Senior Group Tax Manager at Breitling
Choosing a corporate tax platform for Pillar Two is a decision you live with for the next 5–10 years
Longview Tax, Oracle TRCS, Thomson Reuters ONESOURCE, CCH Tagetik – on a demo, they all calculate a top-up tax. The real differences appear in how they handle your compliance reality: jurisdiction-level data collection, safe harbour automation, integration with your consolidation data, and what the GIR filing process looks like at scale.
 Platform Selection
 Tax Process Design
 Project Management
 Data Integration
Before you commit to a platform, you should know exactly how it will handle your Pillar Two data and calculations. We help you find out – with proof, not promises.
How Inulta Implements CCH Tagetik Corporate Tax
Pillar Two sits at the intersection of tax and finance – and implementations fail when partners understand only one side. Inulta – CCH Tagetik Platinum Implementation Partner and Best EPM Implementation Partner 2026 – brings both: consultants who understand GloBE rules and deferred tax mechanics, and 250+ enterprise implementations connecting tax calculations to consolidated financial data. We work alongside your tax advisors – including Big 4 firms – with Inulta delivering the platform and data foundation their advice runs on.
Who Needs to Comply with Pillar Two?
Pillar Two applies to multinational groups with consolidated revenues above €750 million in at least two of the last four fiscal years. The rules are in force in the EU (via the EU Minimum Tax Directive), the UK, and a growing list of jurisdictions applying IIR and QDMTT regimes.
If your group is in scope, three questions determine your readiness: Can you produce jurisdiction-level GloBE data from your current systems? Can you run safe harbour tests and full calculations repeatably, every period? And can you generate the GloBE Information Return without manual re-work? If any answer is no, the compliance process needs a platform – not a bigger spreadsheet.
Frequently Asked Questions
What is BEPS Pillar Two?
BEPS Pillar Two is the OECD’s global minimum tax framework, requiring multinational groups with consolidated revenues above €750 million to pay an effective tax rate of at least 15% in every jurisdiction where they operate. Where the effective rate falls below 15%, a top-up tax applies – calculated under the GloBE (Global Anti-Base Erosion) rules and collected through mechanisms including the Income Inclusion Rule (IIR) and Qualified Domestic Minimum Top-up Taxes (QDMTT).
What is the Global Minimum Tax?
The Global Minimum Tax is the 15% minimum effective tax rate established under OECD BEPS Pillar Two. It applies at jurisdiction level: for each country where an in-scope group operates, the effective tax rate is calculated under GloBE rules, and any shortfall below 15% triggers a top-up tax. The EU implemented the framework through the Minimum Tax Directive, in force since 2024.
Who needs to comply with Pillar Two?
Multinational groups with consolidated revenues above €750 million in at least two of the last four fiscal years are in scope. This includes EU-headquartered groups and foreign groups with EU operations. Compliance requires jurisdiction-level GloBE calculations every reporting period and the filing of a GloBE Information Return. What is QDMTT? QDMTT (Qualified Domestic Minimum Top-up Tax) is a domestic tax regime that allows a country to collect the Pillar Two top-up tax on its own low-taxed entities – before another jurisdiction can collect it under the IIR. Most EU member states have introduced QDMTT regimes, which changes both the calculation sequence and the data requirements for in-scope groups.
What is QDMTT?
QDMTT (Qualified Domestic Minimum Top-up Tax) is a domestic tax regime that allows a country to collect the Pillar Two top-up tax on its own low-taxed entities – before another jurisdiction can collect it under the IIR. Most EU member states have introduced QDMTT regimes, which changes both the calculation sequence and the data requirements for in-scope groups.
What is the GloBE Information Return (GIR)?
The GloBE Information Return is the standardised filing that in-scope groups must submit under Pillar Two, covering jurisdiction-level GloBE data: effective tax rates, top-up tax calculations, safe harbour elections and entity details – typically hundreds of data points per jurisdiction. The first GIR filings are due 18 months after the end of the first in-scope fiscal year, and 15 months for subsequent years.
What data is required for Pillar Two compliance?
Pillar Two calculations require data that typically sits across multiple systems: financial accounting data from consolidation, covered taxes and deferred tax details from tax provisioning, payroll and tangible asset data for substance-based carve-outs, and entity-level information for each jurisdiction. Collecting and validating this data repeatably, every period, is the core operational challenge of Pillar Two – and the reason spreadsheet-based approaches do not scale.
Can Pillar Two compliance be managed in Excel?
For a one-time impact assessment, possibly. As a repeatable compliance process – jurisdiction-level calculations every period, safe harbour tests, audit trails and GIR filing – spreadsheets create unmanageable operational risk. Formula errors, version control and the sheer volume of data points per jurisdiction make a governed platform the standard approach for in-scope groups.
How does CCH Tagetik automate Pillar Two reporting?
CCH Tagetik Corporate Tax provides pre-built GloBE data models, automated ETR and top-up tax calculations (including QDMTT and IIR), safe harbour testing, and direct generation of the GloBE Information Return – on the same platform used for financial consolidation. Because tax calculations run on governed, consolidated data, results are traceable from filing back to source.
How long does a Pillar Two implementation take?
A focused Pillar Two implementation with CCH Tagetik typically takes 15 weeks with an experienced partner – covering data model setup, GloBE calculation configuration and GIR output. Inulta’s phased approach delivers the compliance core first, extending scope as regulatory requirements and safe harbour positions evolve.

Need a custom solution tailored just for you?
Contact us and we will offer our full experience to solve all your business needs in no time.
Contact us here below